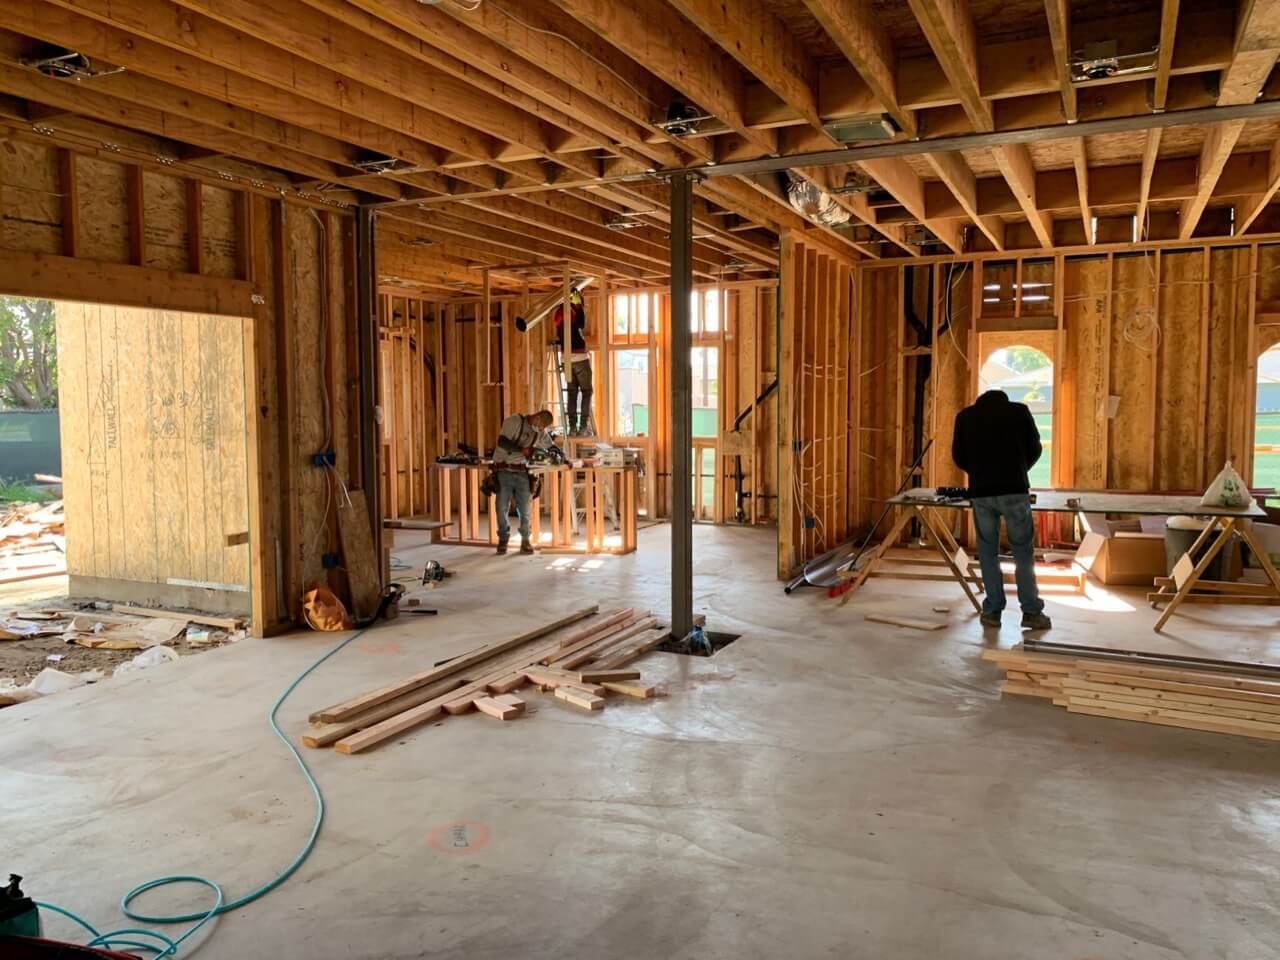
How a HELOC works for home improvements
A home equity line of credit (HELOC) is generally a revolving loan secured by your home. If approved, you can borrow up to a set limit during an access period, and interest is typically charged on the amount drawn—not the full limit. A HELOC is commonly a second lien, so it usually leaves your first mortgage in place while adding another obligation secured by the property.
Terms vary by lender and program. A HELOC may have an access period followed by repayment, when payments may require principal as well as interest. Many lines have variable rates, so ask how the rate is set, how it can change, and what that could mean for payments. Review fees, draw rules, repayment terms, and any rate limits in the agreement rather than assuming a particular structure.
For a home improvement project, compare written contractor estimates with your mortgage balance and any other liens. A lender considers its own property valuation, applicable loan-to-value limits, credit, income, and program guidelines; an online estimate is not an appraisal or a promise of available credit. Include the HELOC payment and your existing mortgage payment in your budget, and consider drawing funds as the work requires. Qualification and terms are subject to credit approval and program guidelines.
Questions about your situation?
Talk it through with a loan officer who knows this market. No forms and no pressure.
Fort Lauderdale home value is a starting point, not an appraisal
Zillow Research reported a Fort Lauderdale home value of $509,743 in September 2026. Use it as market context when planning a project—not as the value of your particular home or a prediction of how much a lender may approve.
Compare project costs with the home and its existing liens
Before choosing a borrowing target, set your contractor estimates beside your current mortgage balance and any other liens. Fort Lauderdale’s top tier home value was $1,189,004, according to Zillow Research in September 2026; that higher-priced segment is a reminder that broad market figures can cover very different properties. Neither that figure nor the citywide home value establishes the value or equity of an individual property.
A lender’s valuation and loan-to-value review may produce a different result from your estimate. Decide which work is essential and what it is expected to cost, then check whether the lender’s review supports the amount you need. When I review a project, I put the proposed budget next to the current mortgage and other liens, then point out which assumptions—such as the home’s value, final contractor cost, or timing of draws—still need to be confirmed. That gives us a practical basis for comparing a HELOC with the costs and obligations of keeping your first mortgage in place.
What I see in this market
A Home Equity Line of Credit, or HELOC, can be an incredibly flexible option for homeowners in Fort Lauderdale looking to fund renovations. This type of financing allows you to draw funds as each phase of your project begins, which means you can manage your budget more effectively. You only pay interest on the amount you actually use, making it a practical choice for those who want to tackle home improvements without the burden of a large upfront cost. This flexibility can really ease the financial pressure during what can often be a stressful process.
Leave room in the household budget for carrying costs
Project financing adds to the obligations you already have, so compare the proposed HELOC payment with your first-mortgage payment and other regular expenses. Broward County’s median property tax was $3,610, according to the Census ACS 5-Year, 2023; account for property costs alongside borrowing costs when assessing what your household can manage. Your own tax bill and loan terms may differ.
Ask for a written breakdown of applicable fees and compare repayment scenarios for the amount you expect to draw. For a variable-rate line, consider how payments could change under the offered terms rather than treating an initial payment as the full cost.
Plan around the project, not a presumed resale gain
Separate urgent repairs from improvements you could defer, and get written estimates that identify scope, materials, and payment milestones. Fort Lauderdale’s starter home value was $303,820 in September 2026, according to Zillow Research. That market measure does not show what a specific renovation will add to a particular home’s value, so do not borrow on the assumption that the project will pay for itself through resale.
Confirm project requirements with the City of Fort Lauderdale or the relevant Broward County authority, and coordinate any planned draws with contractor payments. Keep a contingency in the budget without treating the full approved line as a spending target.
What happens to my HELOC when I sell my house?
In Fort Lauderdale, a HELOC is generally secured by the home, so you should ask your lender how the outstanding balance will be handled as part of a sale. The amount available to pay off liens depends on the sale proceeds, the actual payoff balances, and transaction costs—not the citywide home-value estimate. Zillow Research reported a Fort Lauderdale home value of $509,743 in September 2026, but that is not an appraisal or a forecast of your sale price. Contact your lender and closing professional for the payoff process and figures for your property.
Is a second mortgage different from a HELOC?
A HELOC is one kind of loan that may be secured as a second lien; it is generally revolving, while “second mortgage” can also refer to a separate loan with different repayment terms. For a Fort Lauderdale home improvement project, compare the specific product’s rate, fees, access rules, and repayment schedule while keeping your first mortgage in the calculation. Broward County’s median property tax was $3,610, according to the Census ACS 5-Year, 2023, another property cost to consider alongside either loan’s payments.
The numbers behind this page
Every figure comes from public data on Fort Lauderdale, FL and Broward County. Each one names its source and the month it describes, so you can check it yourself.
