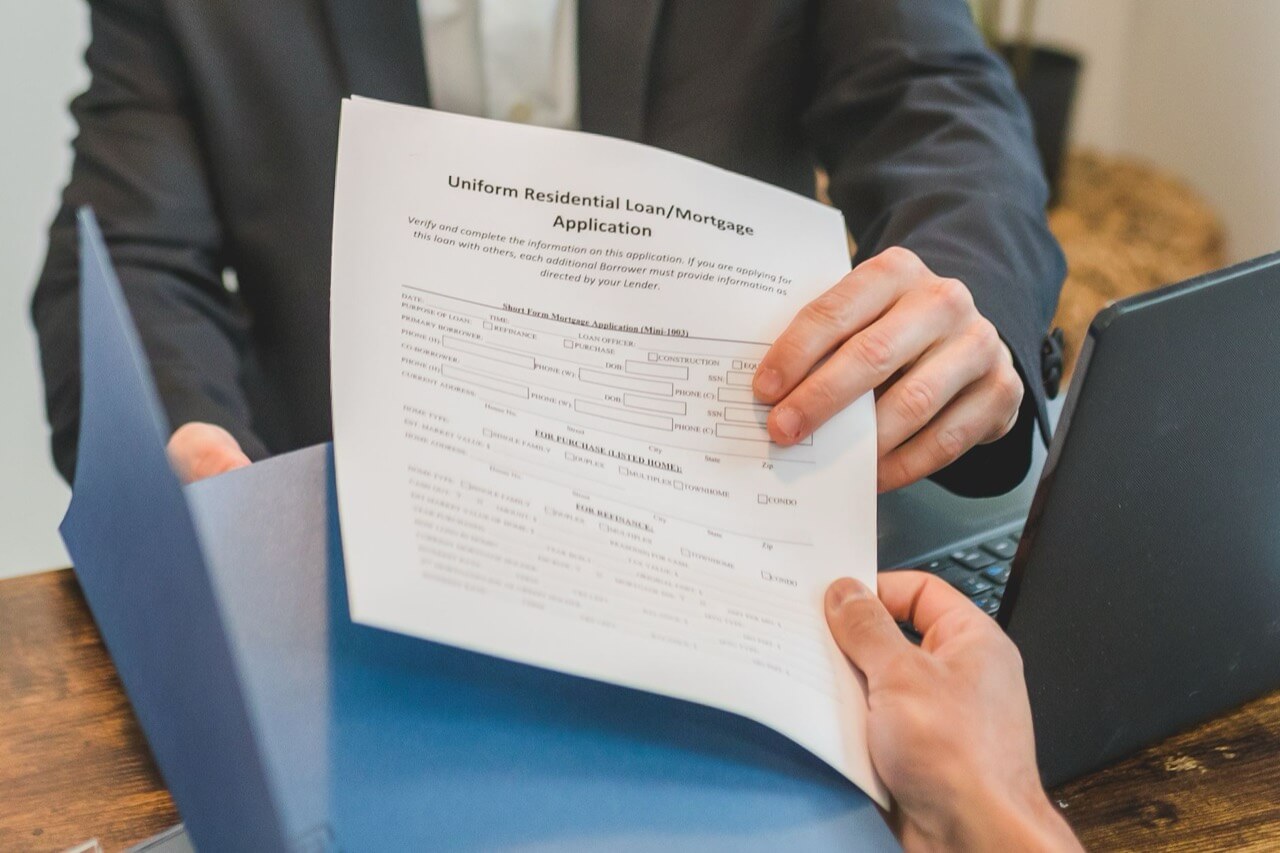
How FHA approval moves from application to closing
FHA approval is a sequence of reviews, not a single decision or a fixed countdown. Preapproval is an early look at the information you provide; it is not final approval of you, the property or the loan. After you have a home under contract, the lender verifies your application, reviews the appraisal and checks the file against FHA and lender requirements.
Be ready to provide identification, income and employment records, bank statements and any explanations or supporting documents the lender requests. Self-employed borrowers may need additional business and income records. The appraisal is a property review, not a home inspection; access, scheduling, report preparation and any follow-up can affect progress.
Underwriting may result in conditions requiring clarification or updated documents. Respond to specific requests, ask when something is unclear, and tell your loan officer if your circumstances change. A decision is not the same as funding: final review and closing preparation remain. Timing depends on the complete file, the property, lender processes and FHA requirements, and approval is subject to credit approval and program guidelines.
Questions about your situation?
Talk it through with a loan officer who knows this market. No forms and no pressure.
Miami's property timeline is not the FHA approval timeline
Homes in Miami took a median of 56 days to go pending, according to Zillow Research, September 2026. That describes the market’s sale pace—not how long an FHA lender takes to approve a particular borrower or loan.
Property access and appraisal coordination matter here
Miami had 5,792 homes for sale, according to Zillow Research, September 2026. With many properties in the market, a buyer’s appraisal is still specific to the home under contract: arranging access promptly helps the appraiser begin, while any questions in the report may call for further review. The inventory figure is context, not a prediction of an individual appraisal’s timing. I go through the document list with borrowers and check in on anything still outstanding, so they know what the lender needs next.
What I see in this market
In my experience, most of the FHA files that encounter delays in Miami are not held up by the lender or FHA itself. Instead, they often stall due to a single missing statement or an appraiser who is unable to access the condo. This is why I maintain a running list of outstanding items and promptly inform you whenever something new arises. By staying on top of these details, I aim to keep the process moving smoothly for you.
A changing Miami market makes preparation useful
Miami recorded 1,000 new listings, according to Zillow Research, September 2026. For an FHA buyer, the practical focus remains the chosen property and a complete loan file—not the number of homes newly listed. Keep requested financial records current and coordinate the appraisal as soon as the property is identified so avoidable follow-up does not slow the lender’s review.
Pending sales show activity, not a loan commitment
Miami had 590 newly pending homes, according to Zillow Research, September 2026. That market activity does not set an FHA underwriting deadline or guarantee a closing date. Once your offer is accepted, stay attentive to lender requests and ask your loan officer what remains outstanding in your own file.
How long does it take to get approved for an FHA loan?
There is no fixed FHA approval timeline: it depends on your documents, the property appraisal, underwriting questions and lender processes. In Miami, homes took a median of 56 days to go pending, according to Zillow Research, September 2026—but that is a market sale measure, not a lender approval estimate. Ask your loan officer which steps in your file are complete and whether anything is still needed.
Is an FHA loan a good option for me?
An FHA loan may be worth considering if its requirements and costs fit your finances, but eligibility and approval depend on your full application and the property. For context, Miami’s median home value was $425,400 in Miami-Dade County, according to Census ACS 5-Year, 2023, while the 2026 FHA one-unit loan limit for Miami-Dade County was $667,000, according to HUD CHUMS FHA Forward Mortgage Limits, 2026. Those figures do not establish your qualifying amount; discuss your income, funds, credit and target home with your loan officer.
Part of this series
The numbers behind this page
Every figure comes from public data on Miami, FL and Miami-Dade County. Each one names its source and the month it describes, so you can check it yourself.
